
Isabel Schnabel of the ECB's Executive Board says central banks must issue reserves directly onchain, not through bridges or private intermediaries. Stablecoins cannot replace central bank money in settlement, she said on Friday.
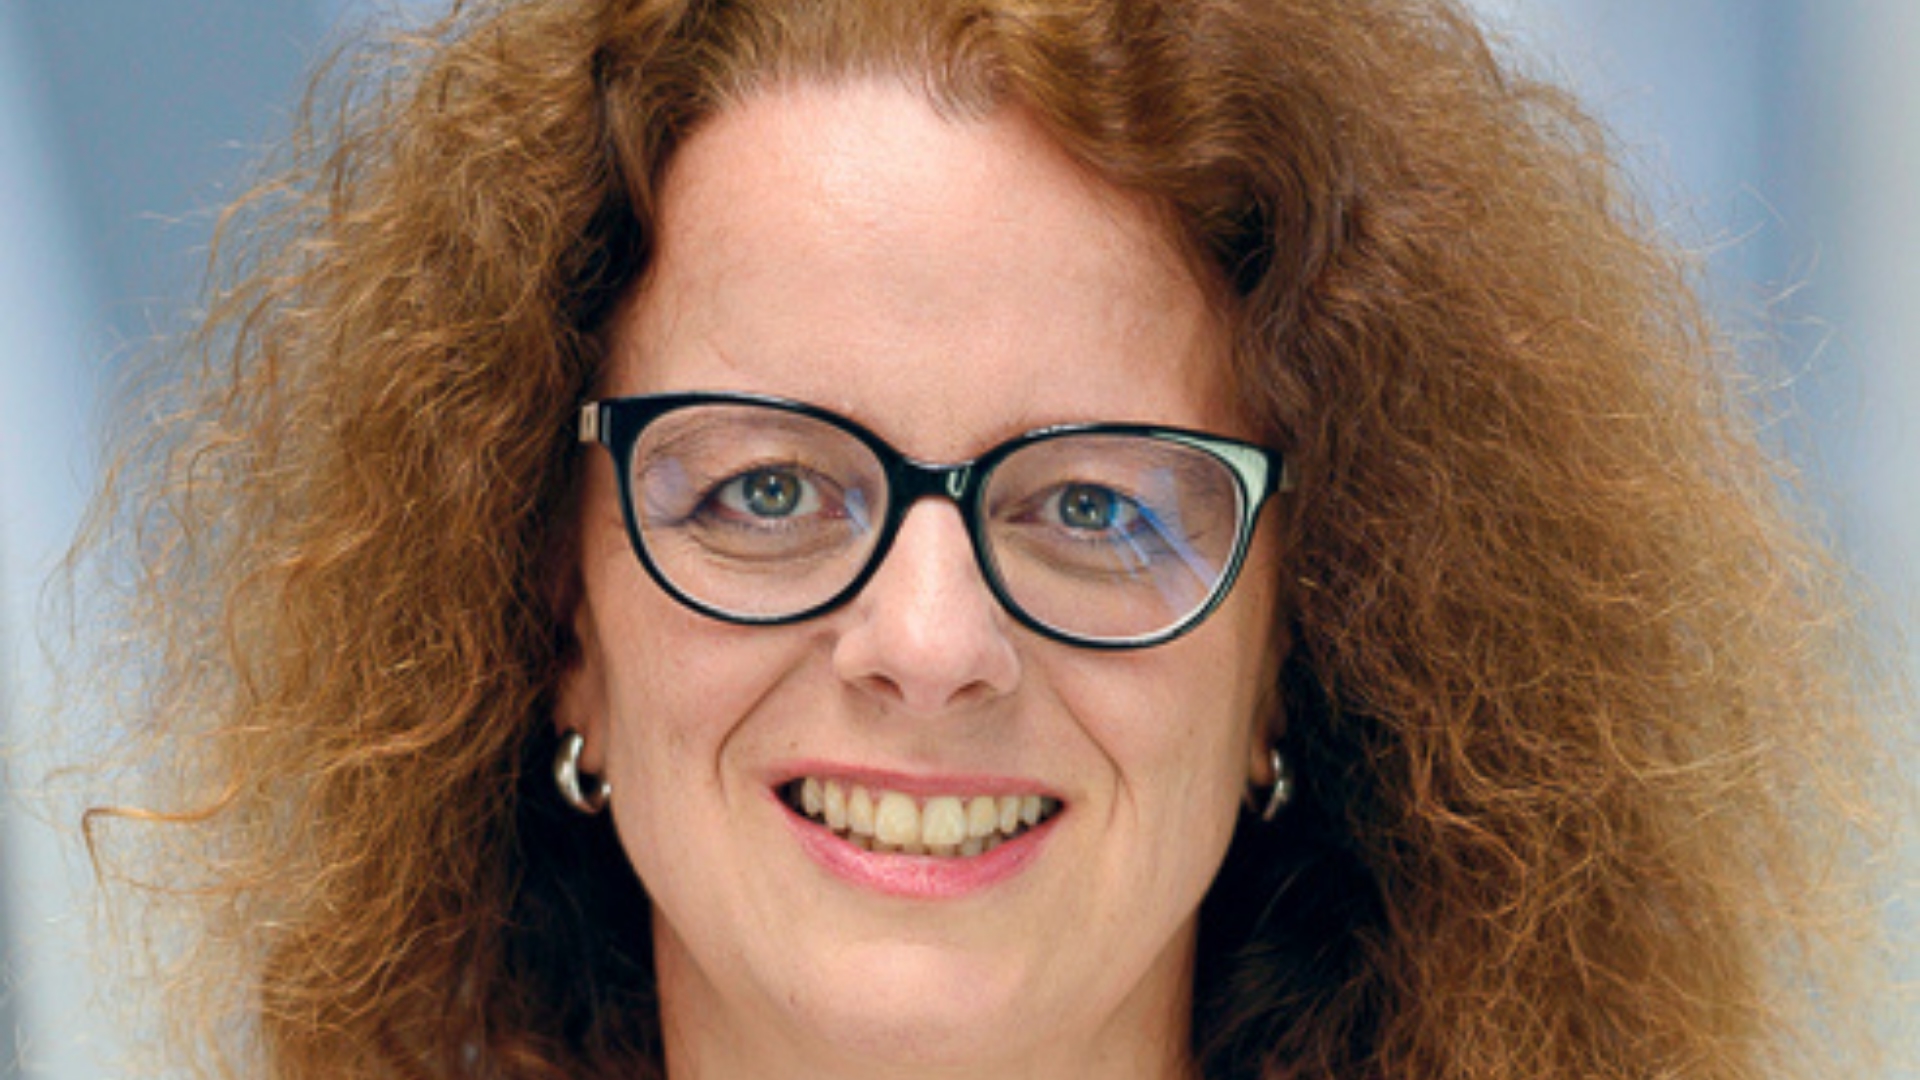
Caption: Isabel Schnabel is a member of the Executive Board of the European Central Bank and gave the address at the Jackson Hole conference on 28 August.
Tokenisation means securities and money are issued as digital units in a ledger that can be programmed. In trading between financial institutions, one thing has been missing: a safe settlement asset inside the ledger. Isabel Schnabel, a member of the Executive Board of the European Central Bank, answered on Friday the question of who should provide it.
"To reap the full benefits, central banks need to go onchain too," Schnabel said.
A settlement asset must be safe, and its supply must be able to grow when demand for liquidity does. Schnabel argued that stablecoins can meet the first test but not the second.
The first can in principle be solved through good design. The second is another matter. A private issuer cannot expand liquidity on its own, least of all when funding tightens and confidence turns abruptly.
That is precisely why the Federal Reserve was created in 1913. Under the old American banking system, the money supply was tied to banks' holdings of government bonds and could not grow in step with demand. The result was repeated panics, among them the one in 1907.
"Stablecoins are best understood as complements to central bank money, not substitutes for it," Schnabel said. Properly regulated, they can widen the range of payment options for households and firms.
The question is therefore not whether central bank money should remain the anchor, but how it gets into the ledgers. Schnabel set out three options.
The central bank can issue tokenised reserves itself. It can build a bridge, synchronising today's payment system with the ledger while the reserves stay outside. Or it can let a private intermediary do the job through an omnibus account.
Only the first produces reserves that actually sit on the chain. In the omnibus model, participants place reserves in the intermediary's account at the central bank and receive tokens in the ledger. Those tokens can be redeemed one for one, but they are not a claim on the central bank — they are a claim on the intermediary. Their value then depends on the intermediary staying sound. And since every ledger will want its own version, settlement risks being split into parallel private claims rather than pooled into one common asset.
In both of the latter models the central bank is left as a passive counterparty on the balance sheet and a gatekeeper over who gets in. It carries on working as it does today and gains nothing from the technology.
If the central bank issues the reserves itself, it can run monetary policy directly in the ledger. Schnabel pointed to Project Pine, a study by the New York Fed and the BIS, which found that smart contracts make implementation faster and simpler.
With collateral and reserves in the same place, a repo can be settled in a single transaction, without messages going back and forth and reconciliation afterwards. The system can call for more collateral automatically, substitute securities in real time, or apply different rates to different counterparties.
This is not fine-tuning, she argued. Tokenisation changes the speed. Margin calls triggered automatically by price movements can force rapid selling and deepen a fall, and more frequent payments that can be netted against each other to a lesser degree raise banks' intraday liquidity needs. The central bank may then have to move faster than today's systems allow. A first step came in January, when securities issued through DLT were accepted as collateral for central bank credit.
The Eurosystem is already under way. Project Pontes connects TARGET Services, the system for real-time gross settlement, to the DLT platforms in the market. But Pontes is more than a connection: the Eurosystem also gets its own DLT platform, where trades can be settled in central bank money.
At the launch next month, legal settlement finality for the cash leg still rests with TARGET2. In time it is to move to the Eurosystem's own solution. Smart contracts and round-the-clock operation come in a later round.
The name means bridges, but Schnabel stressed that the project goes further. It gives the ECB a foot inside tokenised markets, not merely a link to them. In parallel, Project Appia is examining the longer-term architectural choices.
One question Schnabel left open: how the reserves should be issued. The options run from a single shared European ledger holding central bank money, bank deposits and securities together, to several ledgers connected to one another.
What matters is whether the reserves sit in the same ledger as the securities. If they do, both legs of a trade can be executed in one operation, validated by the same mechanism. South Korea is testing such a model through Project Hangang. That also makes it hard to see what private money is for domestically, Schnabel noted: if bank deposits can be programmed, settled in central bank money and work seamlessly alongside securities, they already deliver what stablecoins are meant to offer.
But a shared ledger has its price. The central bank must keep control without becoming the de facto operator of the entire financial market infrastructure. Who is liable when a smart contract fails? Who admits new participants? Who decides on upgrades? Today the Eurosystem owns TARGET Services, while Euroclear and Clearstream own other parts. A shared ledger blurs those lines. It also becomes a single critical point, with the vulnerability that brings.
Schnabel reached no conclusion. She suggested that several ledgers working well together could deliver most of the benefits without the drawbacks. Whichever architecture prevails, she expected old and new systems to run side by side for a long time, perhaps permanently.
Sources: European Central Bank
You have read what you can read for free. With an account you get unlimited access to all news and articles on kaupr.io — and become part of the network of investors, professionals and builders following onchain finance.

