
Sander Andersen, chair of H100 Group, says bitcoin companies below one billion dollars must buy each other. After the August deal he argues that a bigger balance sheet attracts a different class of investor, and that standing still is the real risk.
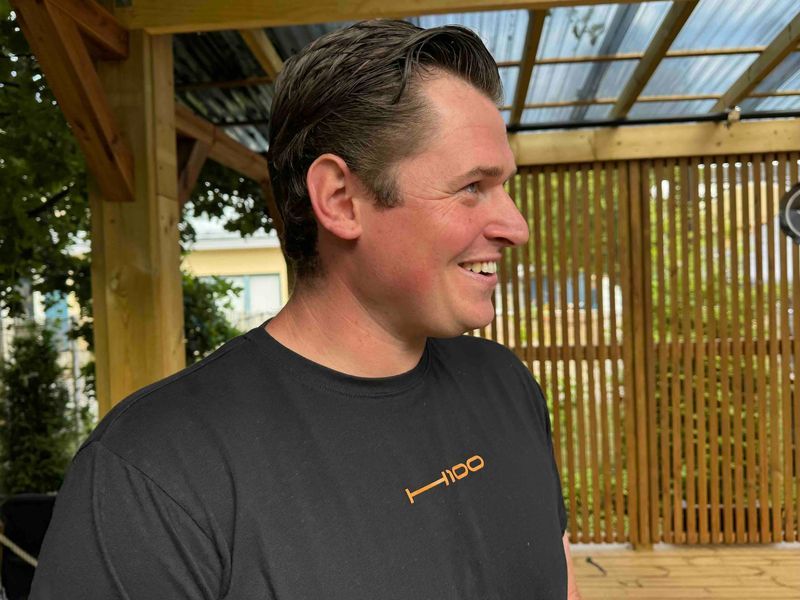
Photo: Sander Andersen at BTCHEL in Helsinki in 2025. In a few weeks he is back on the BTCHEL stage.
Sander Andersen is chair of H100 Group, the Swedish company building a balance sheet in bitcoin. He took over what was in practice an empty listed company and has been behind the change of strategy since 2024. In August the company closed what Andersen calls Europe's largest acquisition in which bitcoin was used to pay for bitcoin. On Sunday morning he summed up on X what the company learned from the transaction, and uses that experience to argue that the industry needs more consolidation.
"The bitcoin industry needs M&A and consolidation," he writes.
Sander Andersen, chair of H100 Group
Andersen's first point is that a bigger balance sheet does not just bring more investors, but different ones. Funds that could not touch the company at one size started calling at the next, he writes.
It is an argument about thresholds rather than about interest: mandates and risk limits shut many managers out of small companies, whatever they think of the case itself.
The same goes for the fight over people, Andersen argues. Small companies lose it, and through an acquisition you do not hire a team, you take over one that has already proved it can execute. He describes that as cheaper, faster and less risky than building the expertise yourself.
Andersen then links the steps together: a bigger balance sheet and a stronger team give a higher market capitalisation, which in turn opens the door to index inclusion, new products and more banks wanting to work with the company. In the end it should mean better liquidity in the stock.
Each step feeds the next, he writes, calling it economies of scale that apply to bitcoin treasury companies just as they do in any other industry.
Andersen argues that the team, the scale and the business built on top of the balance sheet carry a value of their own that investors will price in sooner or later. That premium is what defends mNAV when the market turns, he writes.
mNAV is the ratio between a company's market capitalisation and the value of its bitcoin holding. Below one, the company is priced lower than the bitcoin it sits on — and the option of raising fresh capital without diluting shareholders disappears.
An objection raised in the thread is that M&A does not deliver real growth in bitcoin per share, and that this growth is strongest while the holding is still small. Skip that part, and a company skips much of the flywheel in its early days.
Andersen agrees. If the company can sell shares in size at twice mNAV, it raises equity instead, he writes — and does not do M&A on the terms the market has shown so far. He allows that distressed acquisitions could produce a comparable return, and notes that the industry has yet to see enough M&A in a rising market.
The problem is that nobody gets to pick the timing, he writes.
Andersen points to Michael Saylor having said that Strategy will not do M&A because it is too complex and too risky. With more than 800,000 bitcoin on the balance sheet, few targets are worth the effort.
For companies below one billion dollars, probably measured by market capitalisation, the opposite holds, Andersen argues.
"M&A is not the risk. Standing still is."
Sander Andersen, chair of H100 Group
M&A can be accretive in both bull and bear markets, Andersen argues. Most companies see the value of a bigger balance sheet with less of the bitcoin encumbered.
If these companies were not full of humans, we would have seen far more transactions already, he writes, adding that he expects the industry to be surprised by the yield large balance sheets can create on the day a share-price premium and a market for deals arrive at once.
"Humans are the hard part of M&A."
Sander Andersen, chair of H100 Group
Finally, Andersen raises a question nobody has the answer to: whether the smaller treasury companies will get the same attention in what he calls phase two as they did in phase one. He does not define the phases. The conversations the company has had with investors suggest they will not, he writes.
Sources: Sander Andersen, X
You have read what you can read for free. With an account you get unlimited access to all news and articles on kaupr.io — and become part of the network of investors, professionals and builders following onchain finance.
