
Are stablecoins new payment infrastructure, a useful niche, or overhyped? At the Visa Stablecoin Summit in Oslo, DNB and NBX disagreed, while Nets sat on the fence throughout the panel.
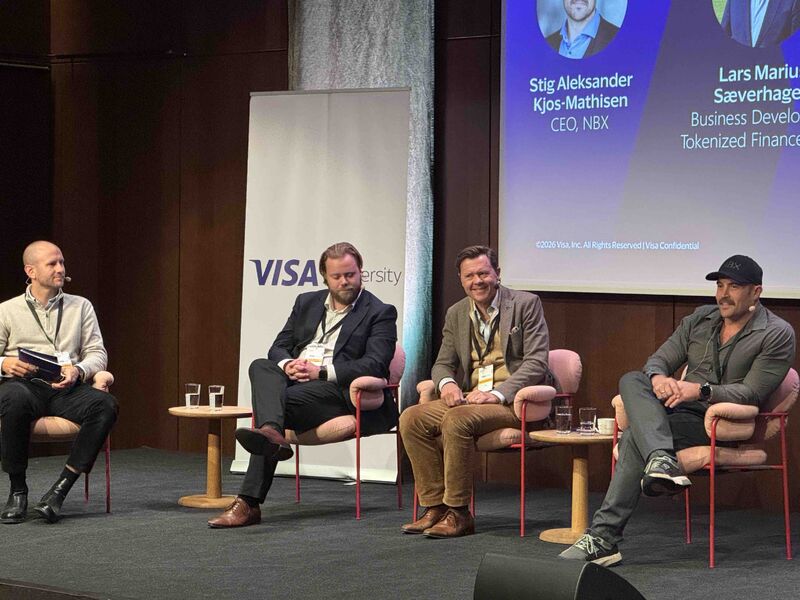
Photo: From left, Viktor Möllborg (Visa), Lars Marius Sæverhagen (DNB), Snorre Corneliussen (Nets) and Stig Aleksander Kjos-Mathisen (NBX) in panel discussion at the Visa Stablecoin Summit in Oslo.
Viktor Möllborg of Visa moderated a panel discussion at the Visa Stablecoin Summit in Oslo with three players who meet stablecoins from different ends of the payment chain. Lars Marius Sæverhagen works on tokenised finance at DNB, where he looks at stablecoins, tokenised deposits and digital central bank money, and also leads the bank's work with Norges Bank on tokenisation. Snorre Corneliussen represented Nets, part of Nexi Group and self-described as Europe's largest payment provider. Stig Aleksander Kjos-Mathisen is CEO of NBX, the Norwegian crypto exchange that has already issued a dollar stablecoin for over a year and is launching euro and zloty versions later this year, alongside a partnership with Visa on a multi-currency card linked to stablecoins.
Möllborg opened with one question to all three: are stablecoins a meaningful new part of payment infrastructure, a useful niche, or overhyped?
"I'd say a useful niche. It's entirely possible to use them today, but I think they'll become even more niche as other forms of money catch up," Sæverhagen said.
Corneliussen was less concerned with the label.
"At Nets, we effectively sell a whole pile of these payment schemes: Visa, Mastercard, Vipps, and now stablecoin. The more, the better. Whether it becomes a niche or something bigger, we honestly don't care. Bring on the 2 percent, there's more than enough room for 50 others alongside it," he said.
Kjos-Mathisen was clearest in his verdict.
"I'm probably biased by who I work for, but I think stablecoins are the very carbon, the building blocks of digital finance. Definitely not overhyped," he said.
For Norwegian consumers, who already have cards, Vipps and bank accounts they trust, Sæverhagen was clear that stablecoins don't solve much domestically.
"I wouldn't say it solves anything for ordinary payments between individuals in Norway, because we have a very well-functioning financial infrastructure. But it does offer some additional possibilities, especially if you want to extend your reach to other countries," he said, citing dollar payments, contact with friends abroad and access to the crypto market as examples.
He also pointed to a survey finding that more Norwegians over 40 own cryptocurrency, including stablecoins, than stocks. If stablecoins give that group a new way to pay that they actually adopt, he said, that would be useful.
Corneliussen started from what the problem actually is. He pointed to Germany, where half the economy still runs on cash, as an example of low trust in digital systems and a desire for anonymity.
"If you think of stablecoins as a form of digital cash, something I could have on my phone and still be relatively anonymous with, that would solve a problem for a German consumer," he said.
He also raised a digital payment that never really arrived: a digital cash card for young people. As an example, he described a typical problem today, where a 14-year-old playing a video game has to borrow their parents' card to buy something in the game, a situation he felt was unnatural compared with a programmable digital currency. He also pointed to AI agents transacting on their own behalf, where today it feels forced to have to hand over a card number and expiry date to an agent, while a wallet linked directly to the agent would make more sense.
Kjos-Mathisen emphasised the payment moment itself.
"You're standing in a queue, there are people behind you, you don't want the payment to fail. A stablecoin-linked card removes the friction between the stablecoin and actually usable money, while you keep the availability," he said.
Paying directly into a wallet requires the recipient to actually have a wallet linked to the checkout system, something he said is still a long way off for most merchants.
Asked which Norwegian consumer segments would adopt stablecoins first, he pointed out that Norwegian payment infrastructure is already fast, just without the programmability a stablecoin offers. He compared the Norwegian market to a film studio that only releases movies on Blu-ray while the rest of the world streams them digitally, and said adoption in Norway would largely follow what happens in the rest of Europe. He thought the first user group would be foreign workers in Norway, such as Poles sending wages home to family.
For merchants, it's about something different than for consumers: conversion, cost, risk and when the money actually arrives. Corneliussen doubted stablecoins would become cheaper than today's card acquiring.
"It probably won't get cheaper than bank acquiring. But it's also about friction," he said.
He highlighted another initiative separate from the bank-led euro stablecoin Qivalis: the ECB's planned digital euro, expected in 2029. Because it's meant to be cost-free for the consumer, he said that simultaneously forces a regulatory requirement that all merchants in the eurozone must support it. For Nets, it's just one more payment scheme to sell, but his point was that pricing has to be regulated into place regardless for anything new to gain a foothold among merchants who are otherwise reluctant to adopt expensive solutions.
Sæverhagen drew an example from his own bank, where a customer called in the middle of the night because she was on her way to Copenhagen and needed the money faster than the settlement times at the time allowed. He drew parallels to how some American courier services have started paying their drivers in gift cards instead of monthly salaries, precisely because the drivers then see the earnings immediately and deliver more. His point was that it doesn't have to be a gift card, it could just as easily be a stablecoin, but that the underlying need is getting paid instantly.
Kjos-Mathisen pointed out that the answer often depends on the merchant's size. Large companies with their own treasury department can handle stablecoins themselves, while most others will likely use an infrastructure service or a crypto service provider like NBX. He said a large share of the lower cost actually reaches the merchant, especially for the biggest players, because many intermediaries disappear. For pure wallet-to-wallet transfers with no intermediaries, there's no compliance cost to speak of either, he noted.
At the same time, he warned against overlooking what card companies actually offer merchants beyond the payment technology itself. If you buy a sofa with stablecoins and the shop goes bankrupt afterwards, you have no one to complain to. With a Visa card, the card company would have stood between you and the transaction.
"Even though I like the idea of direct payment, I see a role for something more than just the currency when settling a purchase. It's not just the technology, it's everything around it that makes it work in practice," he said.
Sæverhagen was most optimistic on behalf of capital markets, not the consumer side. There, he said, the strongest value of tokenisation lies in what he called collateral mobility: the ability to tokenise traditional financial instruments and move them more efficiently between banks.
He described how banks today must tie up capital for a long time when they need short-term liquidity from other institutions, through what's called a repurchase agreement, where securities are posted as collateral. With distributed ledger technology, such financing could in principle be settled in seconds or minutes instead, and programmability makes it possible to automate a bond's entire lifecycle, including payouts through a programmable money layer.
To put the scale in perspective: Sæverhagen estimated the combined market value of Tether and USDC at around $250 billion. DNB alone processes between $100 and $200 billion daily in outgoing foreign exchange trading and settlement through the CLS system, and by its own account is a small player in that context. In three to four days, the bank thus handles more than the entire stablecoin market's combined value, a sign of how much stablecoins need to grow before they carry real weight at the institutional level.
He also noted that banks on the institutional side almost always prefer central bank reserves over a private claim on an issuer when given the choice, simply because central bank reserves are risk-free. That's the reason central bank money must remain the anchor of the system regardless, he said.
To close, Möllborg asked for short answers to two questions with 2030 as the horizon. Will Norwegian consumers knowingly use stablecoins by then? Sæverhagen was guarded, maybe, depending on which variant they encounter, but unsure whether they'd know it's a stablecoin. Corneliussen was more confident: digital cash is needed, and both consumers and their AI agents will send payments with it.
Will stablecoin acceptance noticeably improve the economics for ordinary Nordic merchants by 2030? Sæverhagen had no figures to point to. Corneliussen argued faster settlement creates value regardless for merchants who themselves depend on fast settlement further down the chain. Kjos-Mathisen went furthest: merchants with heavy weekend sales today often have to wait until Tuesday for settlement. With settlement in stablecoins, something Visa already offers, and tokenised money market funds that can generate same-day returns through DeFi, he estimated that could add around 150 extra interest days a year on that portion of the money.
From the floor, Uve Poom of CryptoSwift, a provider of solutions for the anti-money-laundering Travel Rule, raised a question about a concrete obstacle: that the payer's name and invoice number can't automatically travel with the blockchain data itself. The panel's answer was that this is true to some extent, and that when invoicing with settlement in stablecoins or crypto, the payment must be matched to the right invoice separately, since not all blockchains support that kind of information directly.
Sources: Visa Stablecoin Summit, Oslo
You have read what you can read for free. With an account you get unlimited access to all news and articles on kaupr.io — and become part of the network of investors, professionals and builders following onchain finance.