Griffin, a British bank for fintech companies, has raised $20 million in a Series B led by Octagon Partners, valued at over $100 million. The funds go towards card issuing and stablecoins after the company became a licensed bank in 2024.
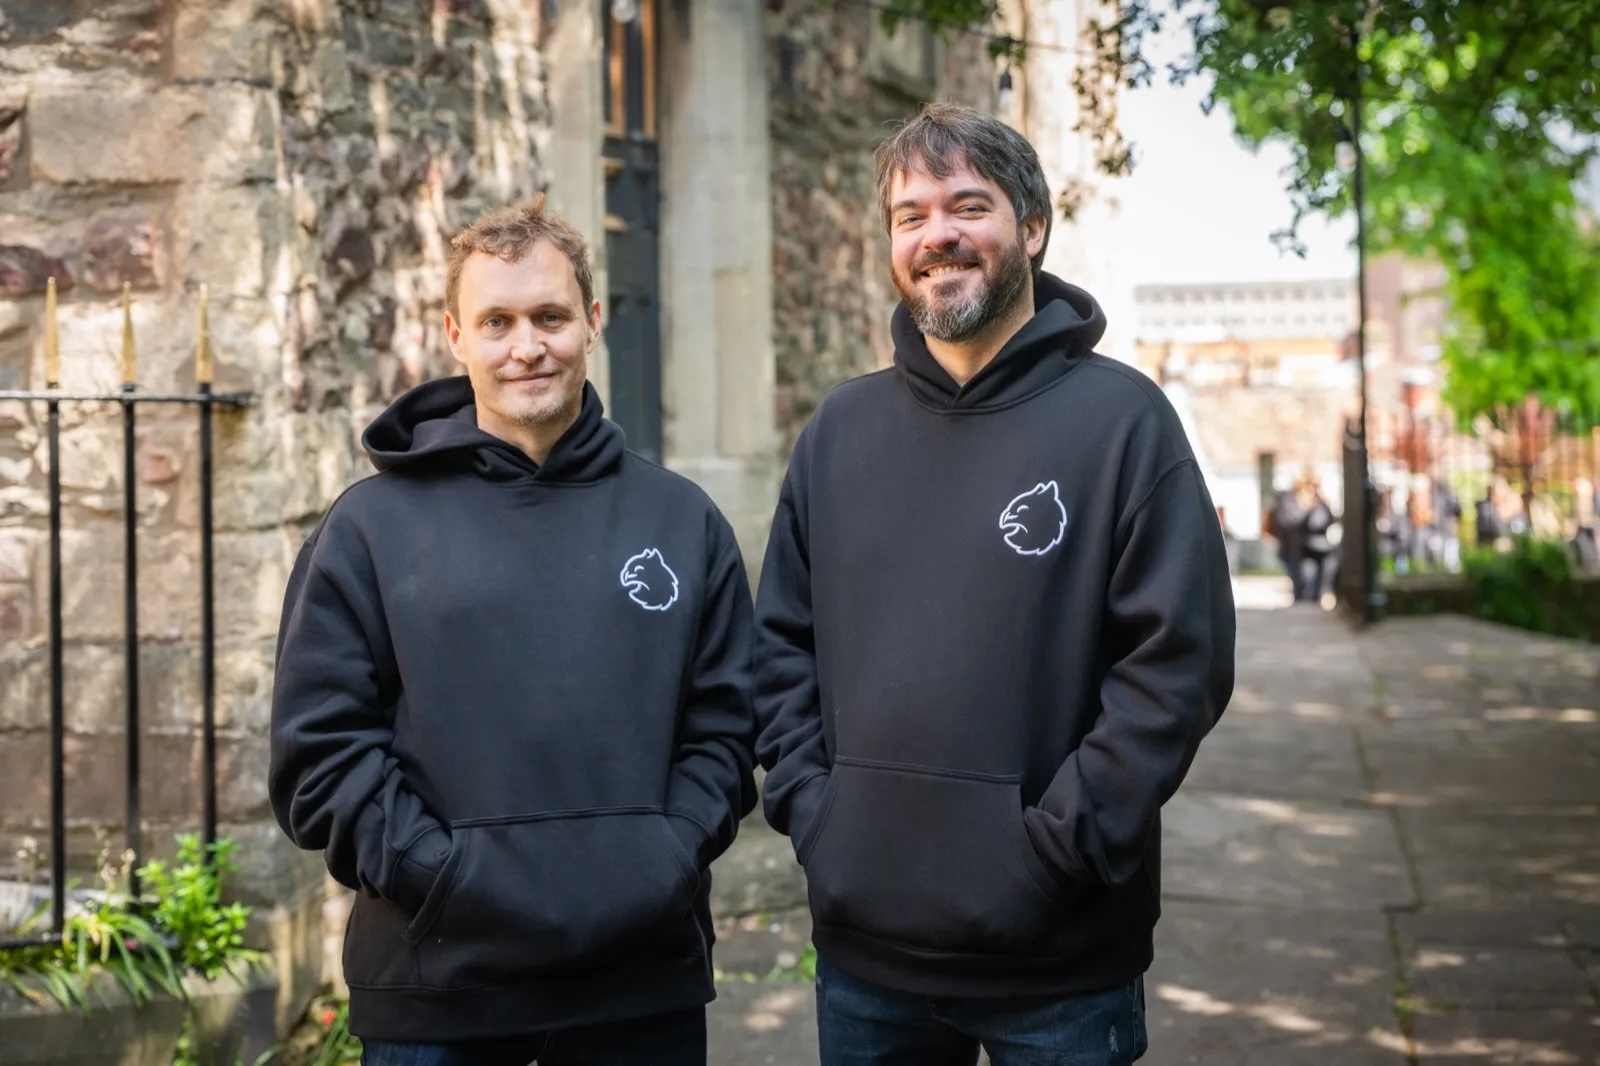
Photo: Griffin's founders, Allen Rohner (left) and David Jarvis.
Banking-as-a-service, or embedded finance, is the model in which fintech companies and other brands offer banking services — accounts, payments, cards — without their own banking licence, by using the infrastructure of a licensed bank in the background. London-based Griffin is one of the providers in this market, and has now raised $20 million in a Series B round led by Octagon Partners. Existing investors Notion Capital, A+ Ventures, NordicNinja and Breega also took part, and the company is valued at over $100 million.
Griffin was founded in 2017 by David Jarvis and Allen Rohner, two engineers from Silicon Valley, and has since recruited banking and technology executives from Form3, Swift, Barclays, Virgin Money and Lloyds. The company started as a provider of banking services that fintech companies and other brands could develop their own products on, without applying for their own banking licence.
In an earlier round, Griffin raised $24 million, led by MassMutual Ventures, NordicNinja and Breega, with Notion Capital and EQT Ventures also participating. The funds were meant to cover regulatory capital requirements still outstanding before the company could exit the temporary status of "mobilisation" and become a fully licensed bank — a status Griffin reached in 2024. Griffin Bank Ltd is today authorised by the PRA, the UK central bank's supervisory body, and regulated by both the PRA and the FCA.
In the announcement of the new round, Griffin describes its own platform as an "agentic banking platform", without explaining what makes it agentic or mentioning AI agents directly. The only concrete reference to artificial intelligence comes from investor Paraag Davé at Octagon Partners.
"Griffin's combination of proprietary technology and AI provides a scaffolding for embedded banking," writes Davé.
Griffin says the capital will fund the launch of debit cards for retail and business customers, with credit cards to follow, as well as reserve banking services and cross-border on-chain payments, including stablecoins. The aim is for the company to reach profitability.
"Cards and stablecoins are the natural next layer for our infrastructure," writes David Jarvis, chief executive and co-founder of Griffin.
The company says it now has more than 80 customers, including Uber, Countingup, Anna Money, Yonder and Prosper, with more than 300,000 underlying customers and close to 10 million payments a year. Griffin reports annual recurring revenue growth of 3.2 times, according to the company's own unaudited figures for the financial year ended September 2026.
Griffin's path through these stages looks like a blueprint several companies may come to follow: first fintech infrastructure for others, then embedded finance as a business model, then its own banking licence, then what the company itself calls agentic finance, and finally cards and stablecoins as new layers on top of the infrastructure.
Sources: Griffin, Vestbee, Finextra
You have read what you can read for free. With an account you get unlimited access to all news and articles on kaupr.io — and become part of the network of investors, professionals and builders following onchain finance.