NBX says its banking application in Latvia could make it the first regulated digital asset bank in the EU, offering deposits, savings and loans secured against digital assets.
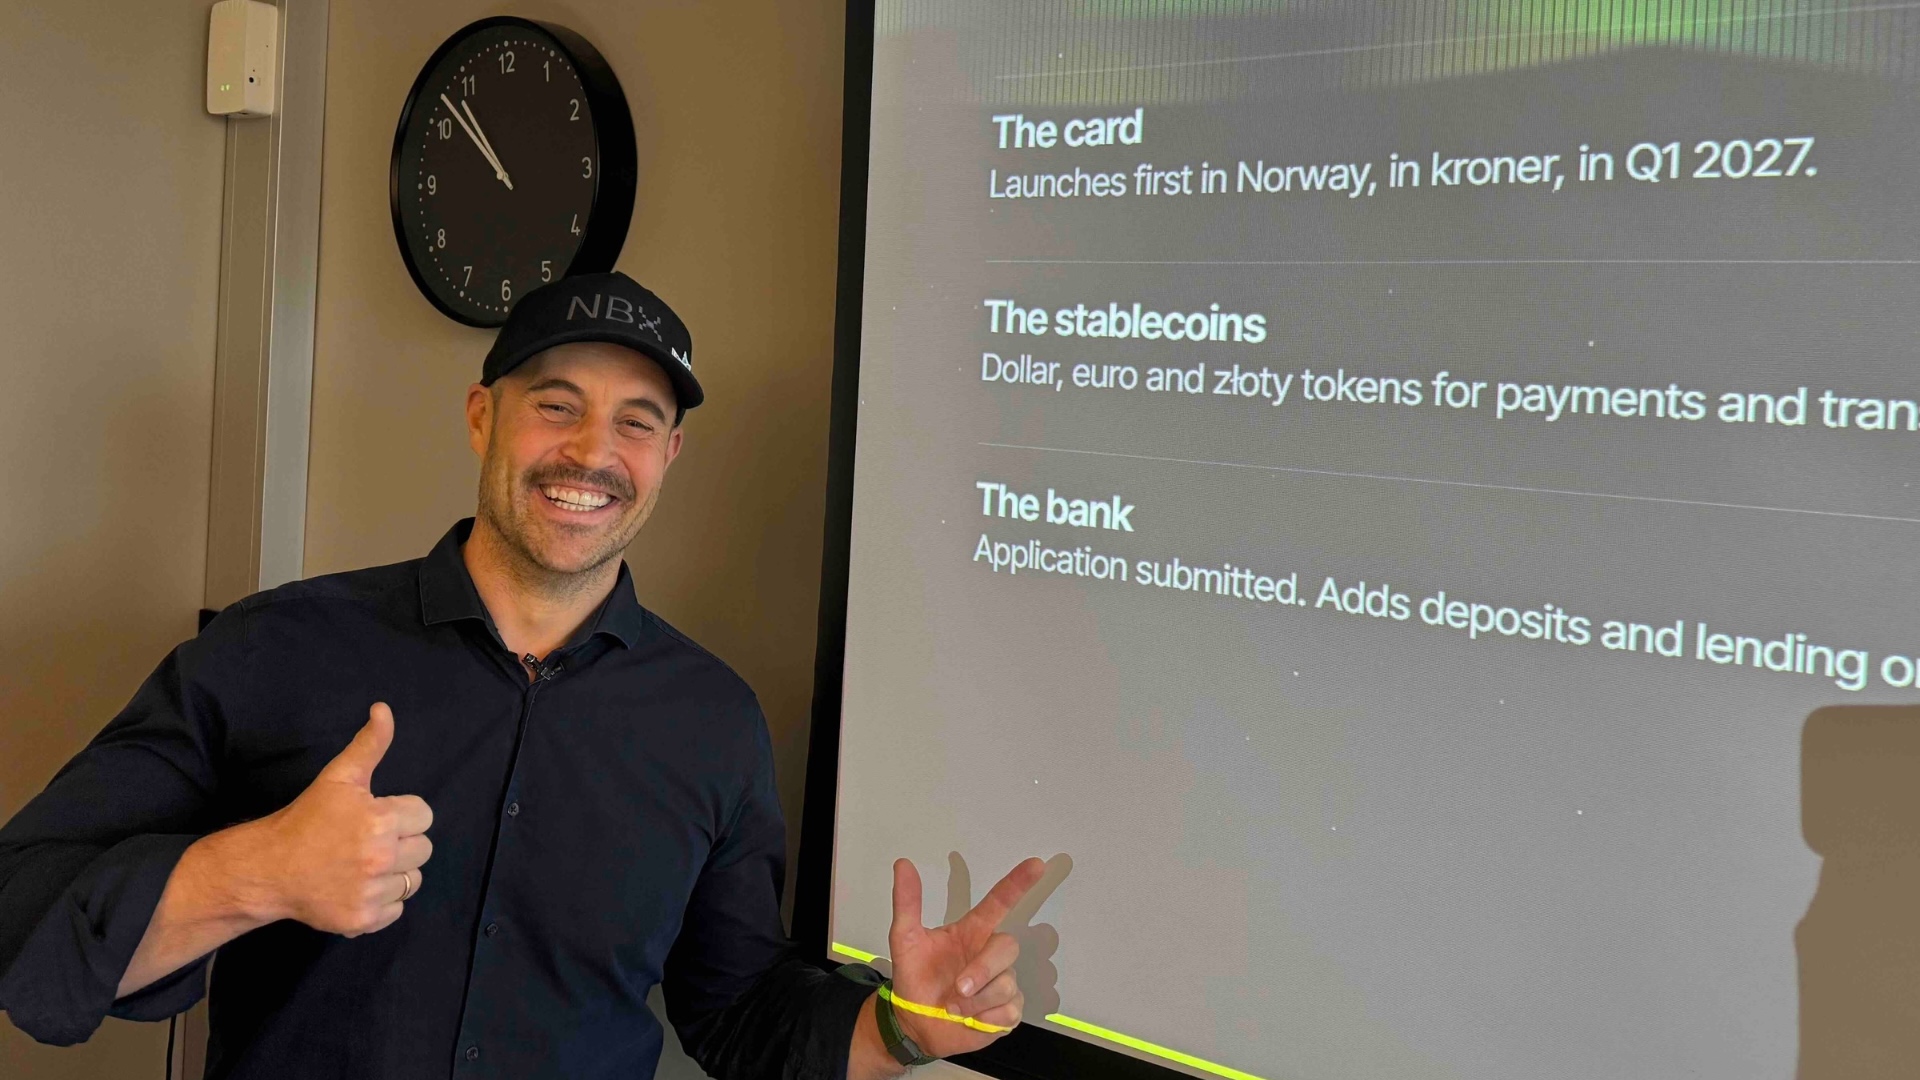
Photo: At the NBX Investor Day, CEO Stig Aleksander Kjos-Mathisen highlighted three exciting product areas: the card, stablecoins and the digital asset bank.
NBX today has around 130,000 registered users, of which 50,100 are KYC-verified customers across 105 countries, according to the company's own customer register. Norway accounts for 64.8 percent of verified customers, Poland for 14.7 percent. The business currently operates under seven MiCA-approved services, passported across the EEA. NBX has already applied for a banking licence in Latvia for what it calls NBX Digital Asset Bank, previously covered by Kaupr in NBX har levert søknad om bankkonsesjon i Latvia. At the investor day in Oslo on 19 November, CEO Stig Aleksander Kjos-Mathisen presented figures and slides showing just how unusual the application is, and what it would actually unlock.
At the investor day, Kjos-Mathisen says it has been years since NBX decided to become a bank. None of the other Nordic crypto exchanges have, in Kaupr's assessment, set out a comparable ambition to become a regulated bank. Kjos-Mathisen says NBX could therefore become the first digital asset bank to be licensed in the EU. Within the EU, he knows of one comparable project: Kraken owner Payward, which has recently agreed to buy Finland's Saldo Finance Oy and its Lithuanian niche bank Saldo Bank – covered by Kaupr in Kraken-eier Payward kjøper banklisens i Litauen. More broadly, he points to Switzerland's Sygnum as the only company he sees as having a comparable strategy. Kjos-Mathisen stresses that an acquisition like Payward's is no shortcut past the regulatory process either: supervisors still have to approve the business model, whether the bank is bought or built from scratch.
According to the company's own presentation, an e-money institution, which is what NBX operates as today, can neither take deposits nor lend money – a bank can. The licence is therefore meant to open up ordinary current accounts for retail and business customers, interest-bearing savings accounts, a credit line tied to the NBX card, and loans secured against digital assets without the customer having to sell them. For launch, NBX has listed Bitcoin, tokenised gold and tokenised silver as planned collateral. The bank is also meant to offer a wallet address linked directly to an IBAN account.
NBX splits the funding side into three: ordinary retail deposits and savings, business deposits, and – according to the company's own presentation – digital asset companies that lack a banking relationship of their own. That last point is a known challenge in the industry, where companies working with crypto assets often struggle to obtain or keep ordinary bank accounts. Deposits are planned in euro, Norwegian kroner and Polish zloty, and the lending side is to consist of the card's credit line and loans secured against Bitcoin, tokenised gold and silver.
NBX gives three reasons for choosing Latvia. First, a dedicated regime for specialised credit institutions came into force in Latvia in 2026, and NBX is among the first applicants under it. Second, a Latvian licence brings supervision from Latvijas Banka within the euro area, with the right to serve customers across the EEA. Third, the company points to banking and compliance expertise it already has in Riga, along with a technology partner that already serves banks in the Baltics.
Kjos-Mathisen stresses that NBX is not leaving crypto behind, but that crypto is now one subcategory of what the company calls digital assets. According to him, digital assets cover crypto assets such as Bitcoin and Ethereum, e-money tokens and stablecoins, tokenised real assets such as gold, and tokenised securities such as shares and bonds. That is why NBX calls itself a digital asset bank rather than a crypto bank.
Kjos-Mathisen describes the whole group as “one customer base, one ecosystem.” Today, customers reach NBX through the NBX app, the Flip wallet and MoneyGram cash points, where NBX is a registered agent – and, according to plan, through the Flex card from the first quarter of 2027. Of the services, trading and custody are already live, the USDM stablecoin has launched, while sister stablecoins EURN and PLT are still planned. Deposits, credit and loans are expected once the banking licence, if granted, is in place.
The different pieces rest on separate licences: NBX's own e-money licence and MiCA approval as a crypto-asset service provider, the banking application through subsidiary NBX Digital Asset Bank, and partner licences under which IDT issues the card and MoneyGram handles the actual money transfer. Kjos-Mathisen expects nine out of ten customers the bank gains in its first year of operation to come via this existing platform, with only one in ten entirely new to NBX.
Sources: NBX, Latvia's Credit Institution Law, Payward
You have read what you can read for free. With an account you get unlimited access to all news and articles on kaupr.io — and become part of the network of investors, professionals and builders following onchain finance.